Chip Index Falls 12% in Its Second-Worst Day on Record
About $2 trillion came off the Nasdaq's market value on 5 November 2026, two days after Democrats took both chambers of Congress and candidates promising data centre moratoriums won in Texas and Georgia.
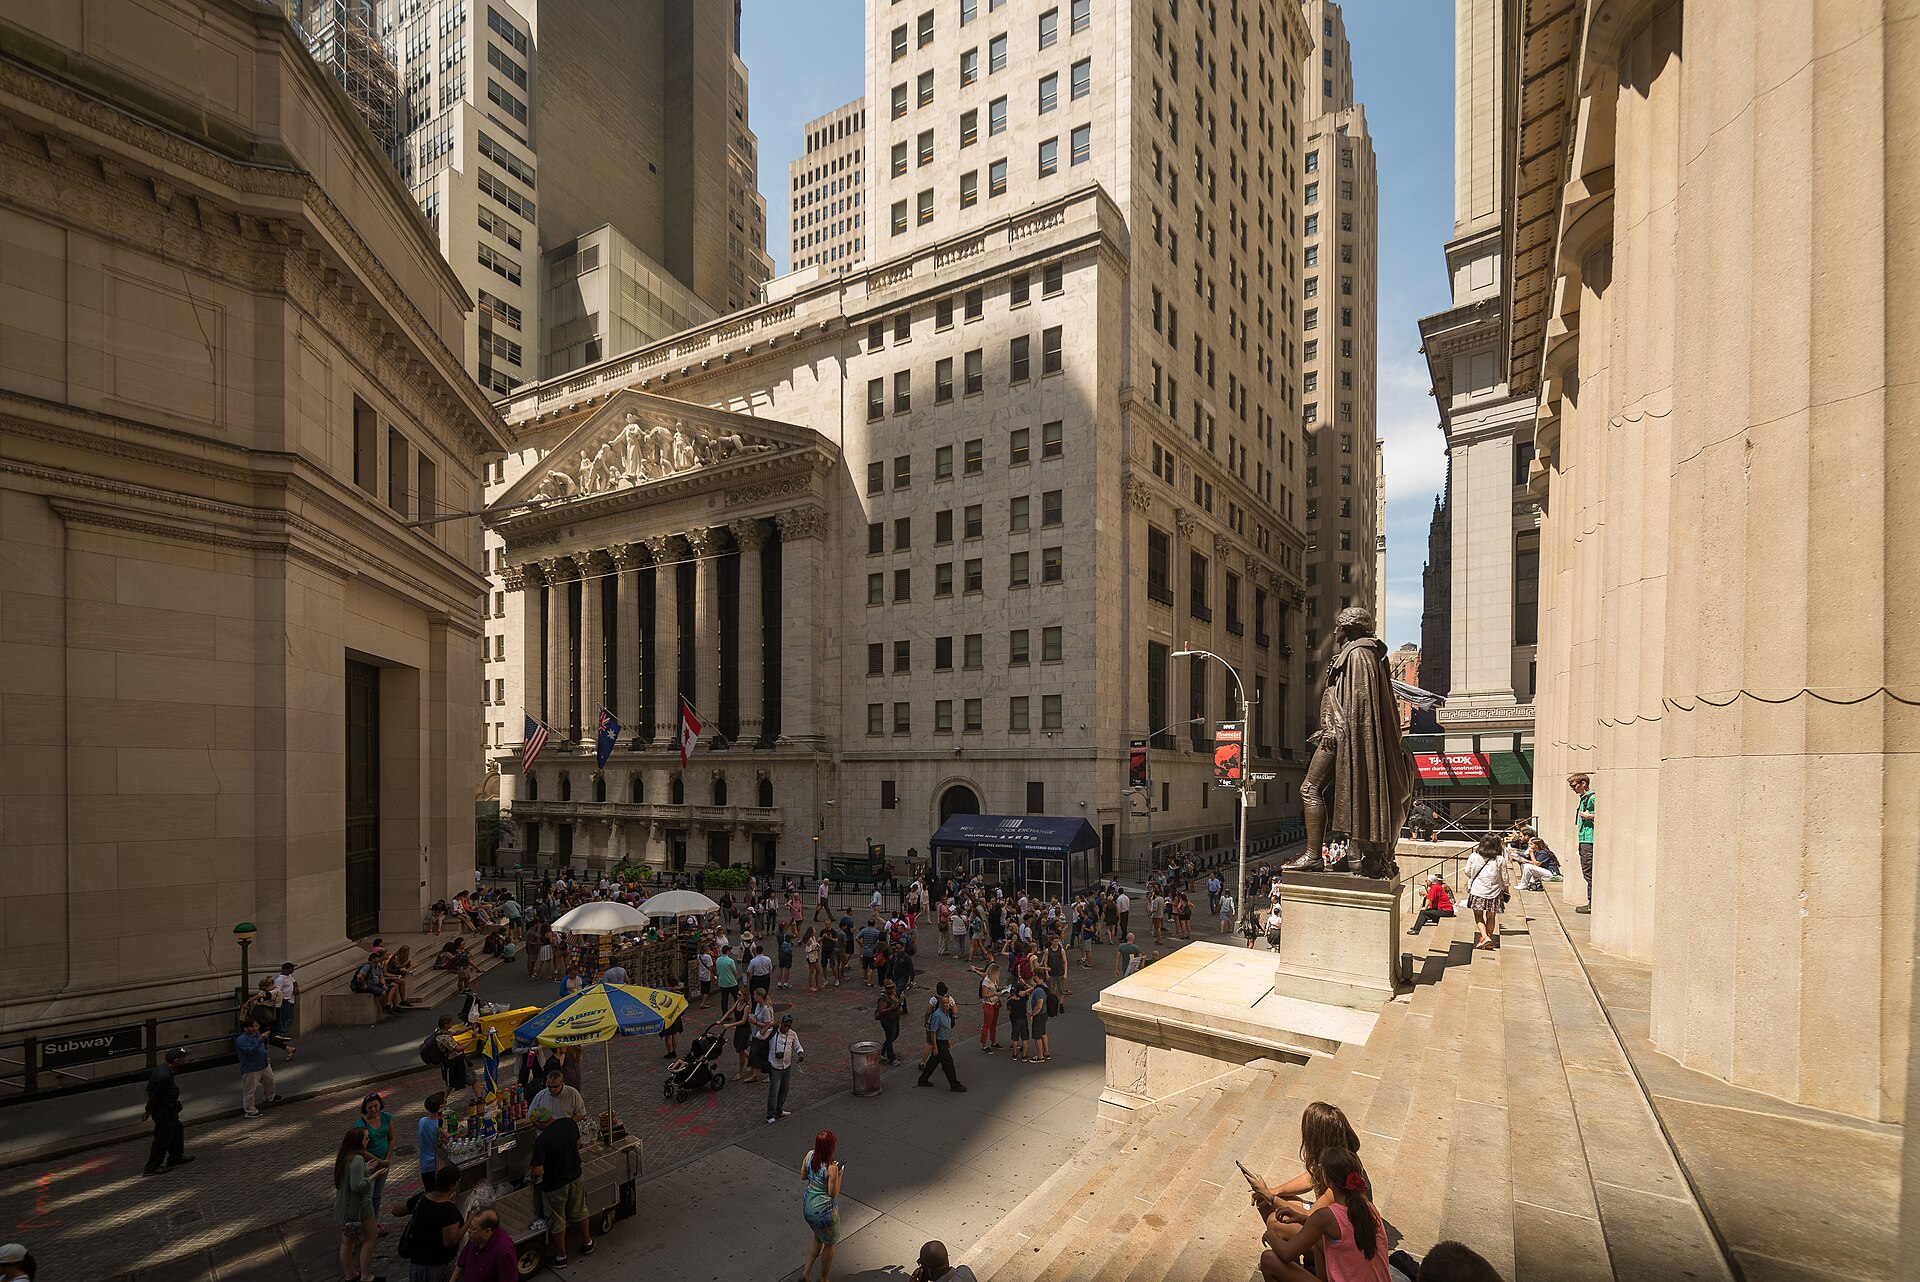
The Philadelphia semiconductor index fell 12 per cent on Thursday 5 November 2026, its second-biggest one-day fall on record, as investors reassessed what a Democratic Congress means for the American data centre buildout. Reuters reported that the Nasdaq closed 5.5 per cent lower, the S&P 500 fell 4.4 per cent and the Dow 3.4 per cent, with all eleven S&P sectors in the red and the technology sector down 7.3 per cent.
Individual names took more. SanDisk fell 22 per cent. Micron Technology, AMD and Marvell each lost about 17 per cent. Nvidia fell 9 per cent. Roughly $2 trillion came off the Nasdaq's market capitalisation in the session, and the index is now down as much as 14 per cent from the all-time high it set a month ago. Bitcoin fell 6 per cent to $75,000. Asian chipmaking exposure went first: South Korea's KOSPI had already dropped nearly 6 per cent to seven-month lows before Wall Street opened.
Falls on 5 November 2026. Change: Philadelphia chip index -12%, S&P 500 tech sector -7.3%, Nasdaq -5.5%, S&P 500 -4.4%, Dow -3.4%, Japan -1.8%.
What the election result actually changed
Democrats won control of both the House and the Senate on 3 November. Reuters noted that candidates who had campaigned in part on moratoriums on data centre construction won in Texas and Georgia, the first and one of the fastest-growing American markets for the buildings. The mechanism investors are pricing is not legislation, which President Donald Trump can veto, but oversight: hearings, investigations and the slow friction a hostile committee can apply to a capital programme that depends on permits granted by people who answer to elected officials.
The blue wave therefore raises the political risk premium around US AI without necessarily derailing the broader AI capex cycle.
UBS put a number on the exposure, telling clients that 30 per cent of planned 2028 American data centre capacity could be at risk under Democratic oversight, a bank estimate rather than an observed figure. The harder evidence is already on the ground and predates the election: Governor Greg Abbott directed the Public Utility Commission of Texas and ERCOT on 3 August 2026 to audit every data centre in the interconnection queue, ERCOT paused energisation of new large loads, and on 21 September Abbott told the Texas Commission on Environmental Quality to halt data centre permits. ERCOT's two reports are due on 10 December.
That context matters for reading Thursday's move as news. The Texas constraint was in place three months before the vote, and the capital-intensity problem was visible in company filings: Alphabet's third-quarter capital spending of $51,355m exceeded its $42,290m of operating cash flow, as Parallax Nexus reported on 28 October. What changed on 3 November was the probability that the constraint spreads and persists past the current political cycle.
The bond market read the same result as dovish
While equities fell, Treasuries rallied. Short-end yields dropped 12 basis points and the curve bull-steepened sharply. Rates markets are no longer fully pricing another Federal Reserve rise until March and imply only about 40 basis points of further tightening in total. Add September's quarter-point increase and the implied cycle is roughly 65 basis points, which would be the mildest in the Fed's history. The Bank of England moved the other way the same day, raising rates for the first time since 2023 on a vote hawkish enough that Standard Chartered now expects another rise in February.
Commodities refused to cooperate with either story. Brent crude had dived nearly 9 per cent overnight on Wednesday, falling below $100 a barrel for the first time in two months and heading for its largest weekly loss since April 2020 on bets that a Democratic Congress makes escalation with Iran less likely. By Thursday's close oil had recovered 3 to 4 per cent. Gold rose 1 per cent, having already gained 5 per cent in two days.
Wednesday and Thursday read the same news differently
On Wednesday 4 November the S&P 500 closed 1.6 per cent higher, the MSCI All-World index posted its biggest one-day gain since late July and the STOXX 600 came within a whisker of August's record. Cheaper oil meant lower inflation risk, which meant a friendlier Fed. By Thursday the same result had been re-read as a threat to the one spending programme holding up index earnings growth. The honest reading is that both days were rational and the market simply has no settled view on which effect dominates, which is what a 12 per cent move in a sector index looks like from the inside.
The counter-argument is statistical and comes from Deutsche Bank strategist Jim Reid, who pointed out that in 20 of the 20 midterm elections since the Second World War, the S&P 500 has been higher a year later. Truist's Keith Lerner, who remains bullish, put the near-term position more plainly: "We are now seeing something of a buyers' strike in tech. The rubber band could get stretched further to the downside."
What is not known is whether any announced capital programme has actually changed. No hyperscaler has cut a disclosed capex guidance figure since the election, no committee has been named and no hearing scheduled, and the incoming Congress does not sit until January. Friday's October payrolls report, forecast by economists polled by Reuters to show a net 65,000 jobs added and unemployment unchanged at 4.2 per cent, will test the other half of the thesis, which is that the AI buildout has not yet cost anyone a measurable number of jobs.
What happens next?
- The October US payrolls report is published on 6 November 2026, with economists polled by Reuters expecting 65,000 jobs added.
- ERCOT is due to file two reports on 10 December 2026 on which Texas data centre projects qualify for its Batch Zero queue and on community impacts.
- The new Congress is seated in January 2027, when any oversight of AI infrastructure would begin in practice.
- Rates markets now put the next Federal Reserve rise in March 2027, a date that will move with inflation and payroll data.
Related topics
Sources & references
- 01Trading Day: A November 5 market bonfire — ReutersnewsReuters column by Jamie McGeever, 5 November 2026, carrying the day's index and single-stock moves, the $2 trillion Nasdaq figure and the Lerner quote.
- 02AI stocks, oil fall as investors bet on change after US election 'blue wave' — ReutersnewsReuters market report, 5 November 2026, with the Loo and Reid quotes, the Brent move and the Texas and Georgia election results.
- 03Get Off of My Cloud: Texas Moratorium on Data Center Grid Connections Disrupts U.S. Project Pipeline — RBN EnergyreportDates for the 3 August 2026 ERCOT audit directive, the 21 September TCEQ permit halt and the 10 December ERCOT reports.
- 04US weekly jobless claims at 57-year lows amid low layoffs — ReutersnewsSource for the 65,000 payrolls forecast and the 4.2 per cent unemployment expectation for the October report.
More from Business
Fed Holds Rates With Two Votes for a Quarter-Point Rise
The Federal Open Market Committee kept the federal funds rate at 3.75 to 4 per cent on 28 October 2026 after raising it in September. Two members dissented in favour of a further quarter-point rise, and the committee changed one word in its growth assessment.
Anthropic's S-1 Shows $16.3bn of Revenue and a $693m Loss
Anthropic's Form S-1 reports $16,286m of revenue for the first half of 2026 against $1,163m a year earlier, a $693m operating loss, and a $80,748m net loss of which $72,388m is the change in fair value of convertible notes and similar instruments. The filing leaves the price range and share count blank.
Citi Wins a China Brokerage Licence After Five Years
China's securities regulator cleared Citigroup Global Markets Holdings to establish a wholly owned brokerage in Shanghai, ending an application that had been pending since December 2021 and returning Citi to onshore securities six years after it left its Orient Citigroup joint venture.
SpaceX Spent $19.6bn of Capex in a $4.4bn Profit Quarter
SpaceX's results for the quarter to 30 September 2026, filed with the SEC on 20 October, show the renamed Super Intelligence segment overtaking Starlink on revenue while absorbing $16.4 billion of capital spending in three months.